
September 2026 Denver Metro Market Update
Mortgage rates dominated the Denver real estate market this September. Understanding what’s moving them and how financing can affect an offer is useful for buyers and sellers alike. The month’s data showed fewer sales and more inventory, while individual properties continued to produce very different results. For anyone planning a move or simply following the market, there is plenty to learn from both the numbers and the conversations happening around offers.
What September’s Numbers Tell Us
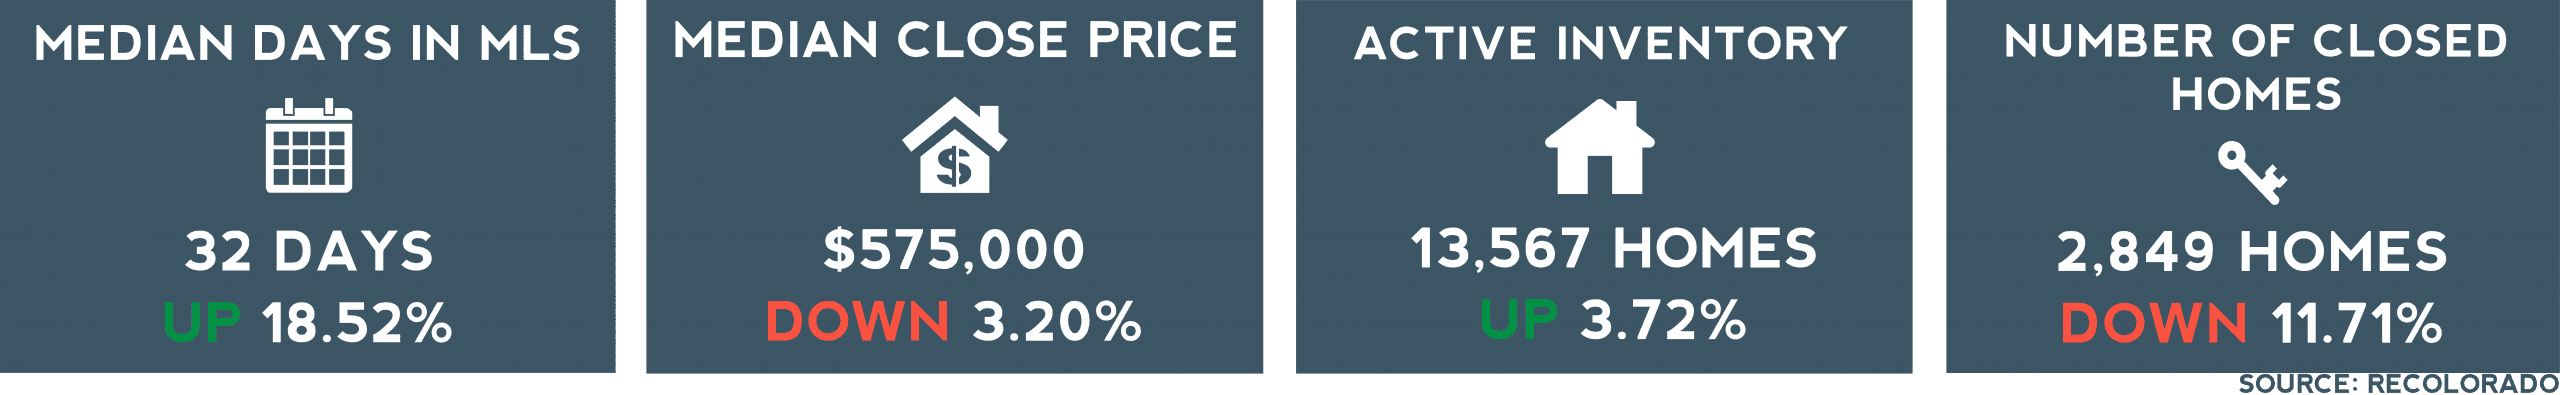
September recorded 2,849 closings, down 11.71% from August and 21.39% from a year ago. Active inventory rose 3.72% from August to 13,567 homes, while new listings were essentially unchanged. Median days in MLS increased from 27 to 32, although that remained below last September’s 35 days. Buyers have more homes to compare, and sellers are working on longer timelines than earlier in the season.
Local coverage has compared sales activity with 2008, but sales counts alone don’t tell us whether the same conditions are present. September’s overall median close price was $575,000, down 1.88% year over year. Closing data also lags: many September sales began as August contracts, when DMAR reported rates around 6.7%, before reaching roughly 7.5% by September’s end. Pending sales fell 6.07% from August. October and November closings will show more of that rate change, making new contracts and showing activity useful measures to watch in the meantime.
What’s Moving Mortgage Rates
Mortgage rates respond to several forces at once. Inflation, government borrowing, and geopolitical uncertainty are influencing long-term interest rates in real time. These factors affect the 10-year Treasury yield, a benchmark that mortgage rates tend to follow. A Fed rate change announcement is part of that picture, but it doesn’t determine mortgage rates alone.
The other piece is the mortgage spread: the gap between Treasury yields and mortgage rates. Mortgage investors account for additional costs and risks, including uncertainty about when borrowers might refinance or pay off their loans. That gap can widen when markets are volatile and narrow as conditions settle. This explains why a favorable economic report doesn’t always produce a better mortgage quote. Both Treasury yields and the spread matter, and improvement in either can help borrowing costs.
Financing Is Part of the Offer
Involving a lender before writing an offer can help buyers and sellers find an agreement that works for both sides. A lower purchase price reduces the amount financed, while a seller credit can cover eligible closing costs or pay points toward a permanent rate buydown. Depending on the loan, a credit may do more to improve the monthly payment or reduce the cash needed to close. Comparing those options helps the buyer understand the payment and overall cost, while the seller considers the net proceeds.
Rate-lock planning can also help buyers move forward with confidence. Going under contract doesn’t always require an immediate lock, but waiting can bring higher rates or potential savings. A lender can explain the timing, costs, and options available, including whether an eligible seller contribution could cover lock-related fees. Working through those questions early gives buyers a clearer understanding of their financing and sellers another way to help an offer come together.
Individual Homes Still Have Their Own Market
Denver’s market continues to vary by property type, location, and price range. September’s median detached close price was unchanged from a year ago, while the attached median declined 6.28%. Buyers weigh condition, features and ongoing ownership costs differently, so the metro-wide averages can only tell part of a home’s story.
For sellers, the most useful perspective comes from comparable homes and buyer feedback. Understanding what attracts interest and where buyers hesitate helps guide decisions about pricing, presentation, and concessions. For buyers, looking closely at those same factors can reveal opportunities that a broad market headline might miss.
Moving Forward With a Plan
September brought fewer sales, more inventory, and higher borrowing costs. For buyers and sellers, the next step is understanding how those conditions affect their particular move. Comparing nearby properties, reviewing buyer feedback, and involving a lender early can help identify where an adjustment in price or terms could bring an agreement within reach. Buyers gain confidence by knowing what they can afford and how to structure an offer. Sellers benefit from a clear plan to attract interest and respond to it.